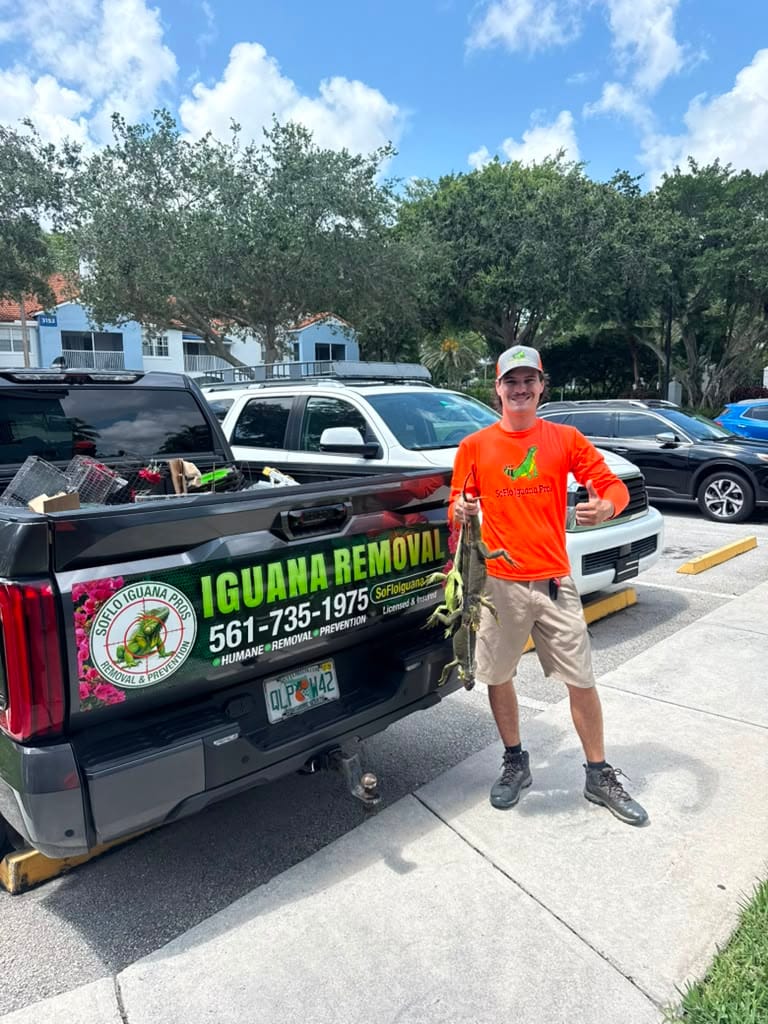
It's not box-ticking. On a seawall or a two-story roofline, the difference between insured and not is who pays when something goes wrong.
'Licensed and insured' gets said so often in this business that people tune it out. That's a mistake. Iguana removal isn't a desk job — it's climbing dock pilings, working the edge of a seawall over water, and getting up on flat roofs and tile. Those are exactly the places accidents and property damage happen, and the paperwork decides who's holding the bill when they do.
I carry it because I'd want it on my own property, and I'll explain plainly what it protects you from.
What insurance actually covers you against
The scenarios aren't hypothetical. Wildlife techs work at height, over water, and around your hardscape, and a homeowner without a covered contractor can end up personally exposed.
- A tech falls off your seawall or roof — insurance, not your homeowners policy, should answer for the injury.
- A ladder goes through your screen cage or a tile cracks — liability coverage handles the repair.
- Damage to a neighbor's property during a job on the shared waterline.
- The general reassurance that the person on your roof is accountable to more than a handshake.
Why the license matters too
Green iguanas are a non-native species handled under specific Florida rules — how they're trapped, how they're transported, and how they're dispatched all have to be done correctly and humanely. A licensed operator knows those rules and follows them, which keeps you clear of a situation you didn't know you were creating by hiring the wrong person.
It also tends to correlate with the rest of the work being done right. Someone who does the paperwork properly usually does the trapping and burrow work properly too.
How to verify it — don't just take the word
Ask for the certificate of insurance and actually look at it; a real company sends it same-day without friction. If you're a board or a property manager, have the association named on the COI. We hand ours over as a matter of course, and if you're hiring us for a community, we'll name the association so your treasurer has the paper trail for the file.
You can start the conversation on our /contact page — the free property walk is also where we bring proof of coverage, so you're not taking anything on faith.
Questions we hear
How do I confirm a company is really insured?
Ask for the certificate of insurance and read it — coverage type, limits, and that it's current. A legitimate company sends it the same day without hesitation. If you're a board, ask to be named on the COI so the association is covered, not just the contractor.
What could go wrong if I hire someone uninsured?
If they're hurt on your roof or seawall, or they damage your property or a neighbor's, you can end up personally exposed with no coverage to fall back on. The savings on a cheaper uninsured quote disappear fast the first time a ladder goes through a screen cage or someone falls.
Services in this guide